Why the Square Footage in a Listing May Not Match the Mortgage Appraisal
A home’s advertised square footage can influence which properties buyers tour, how they compare asking prices, and what they expect from an appraisal. But the number in a real estate listing is not always the same as the living area reported by a mortgage appraiser. Differences can occur even when nobody intended to provide misleading information. Understanding why can help buyers evaluate a home more accurately.

Square Footage Depends on What Is Counted

Listings may draw measurements from tax records, prior listings, builder plans, or information supplied by the seller. Those sources do not always use the same definitions or reflect later changes to the property.

An appraiser typically follows measurement and reporting requirements applicable to the assignment and loan program. That can mean distinguishing finished above-grade living area from basements, garages, porches, and other spaces. A room can be attractive and useful without qualifying for the same square-footage category as the main living area.

Finished Does Not Always Mean Included

Consider an enclosed porch with new flooring and heating, a finished basement with a recreation room, or a converted garage used as a bedroom. These spaces may add utility, but their treatment in an appraisal depends on factors such as location relative to grade, access, finish, and applicable measurement standards.

A homeowner may think of every finished room as part of the home’s size. An appraiser may report some of those areas separately. That does not automatically mean the spaces have no value. It means they may be analyzed differently.

Additions Can Create Record Discrepancies

A property might have gained a family room or bedroom after the original construction. If local tax records were never updated, the public square-footage figure may be outdated. The reverse can happen when records include areas that do not meet the appraisal’s living-area definition.

Permits and building records can help clarify what was added and when. If the addition was not permitted, the lender may need more information about the work, depending on the circumstances and loan requirements.

Why the Difference Matters to Financing

The appraiser estimates market value using the home’s characteristics and relevant comparable sales. A smaller reported living area can change how the property compares with nearby homes. But a square-footage discrepancy does not automatically mean the appraisal will come in low.

Location, condition, layout, quality, and the market’s response to finished spaces all matter. The important question is whether the valuation reflects the property’s actual features and how buyers in that market value them.

Steps Buyers Can Take

Ask where the listing’s square-footage figure came from. During a showing, note any rooms that appear to be converted garages, enclosed patios, or basement areas. If the stated size is central to your decision, consider asking for available floor plans or discussing independent measurements with your real estate professional.

When the appraisal arrives, review how different spaces were classified. Your lender can explain the next steps if the report identifies a material discrepancy.

Square footage is a useful starting point, not a complete description of a property. Knowing how it is measured can help you compare homes with more confidence and avoid surprises during mortgage approval.
Why an Easement on the Property Could Raise Questions During Mortgage Approval

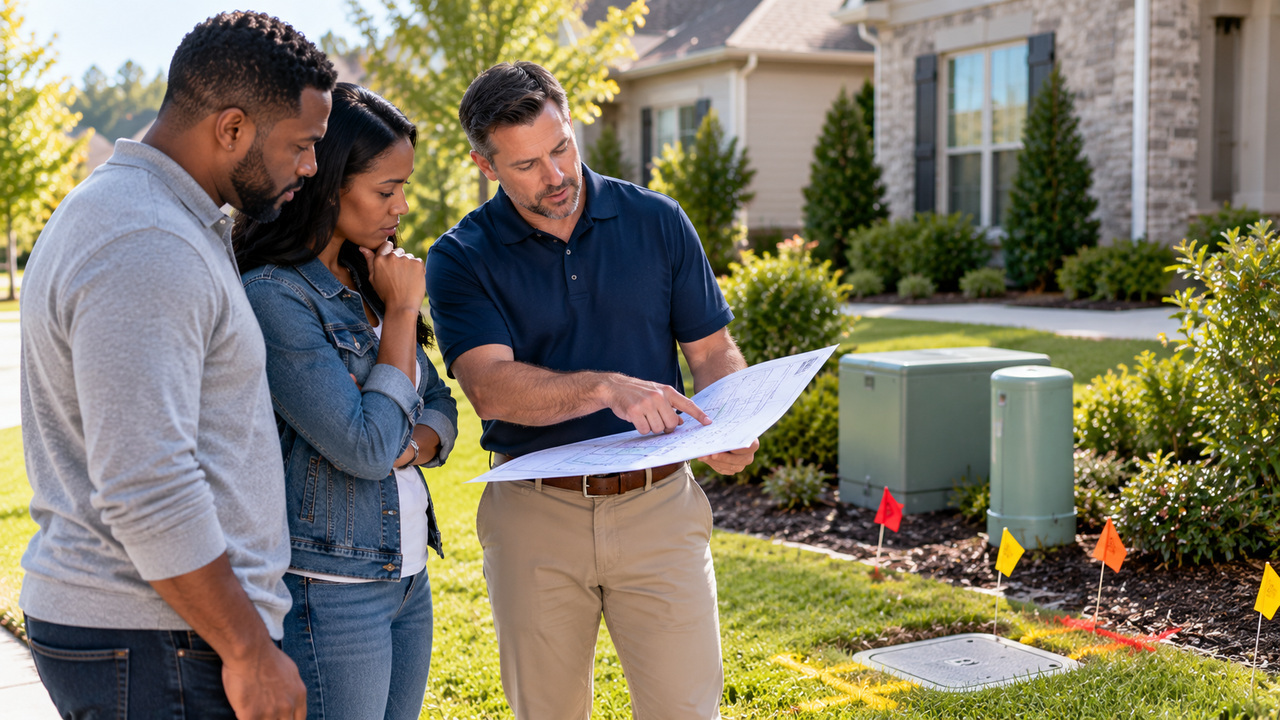
You may love a home’s layout, yard, and neighborhood without realizing that someone else has a legal right to use part of the property. That right may be an easement. Easements are common, and many cause no problems at all. Still, buyers should understand what an easement allows, where it is located, and whether it affects the property’s value or access before moving forward with a mortgage.
What Is an Easement?

An easement generally gives another party a limited right to use land owned by someone else. Utility companies may have easements to maintain power lines, pipes, or other infrastructure. A neighbor may have an access easement to cross a driveway or road. Drainage and conservation easements can also restrict how portions of a property are used.

An easement does not necessarily mean the other party owns the land. It does mean the homeowner’s use of that area may be limited by recorded rights or agreements.

Why Lenders Pay Attention

A mortgage lender needs confidence that the property has acceptable access, can be used as intended, and can be sold if necessary. An easement that allows utility maintenance along a rear fence may have little practical effect. An easement running through a proposed building site or limiting access to the house can be more significant.

Access deserves particular attention. If the only way to reach a property is across land owned by someone else, the lender may need evidence that the access rights are legally established and adequate for the loan program. A friendly handshake with a neighbor may not be enough.

The Title Review Can Reveal Surprises

During the purchase process, the title company typically searches public records for matters affecting ownership. Recorded easements may appear in the title commitment or related documents. Buyers should read those exceptions rather than assuming every listed item is routine.

A survey, when available or required, can help show where an easement crosses the lot. The exact location matters. A ten-foot utility strip at the edge of a yard is very different from a right-of-way cutting through the middle of the driveway.

How an Easement Can Affect Value

An appraiser considers the property’s legal and physical characteristics, including restrictions that influence typical buyer demand. Not every easement reduces value. Some are standard features of developed neighborhoods. Others may affect privacy, expansion plans, parking, or the ability to install a pool or outbuilding.

The impact depends on the terms of the easement, its location, and the local market. Buyers should not assume an easement is either harmless or a deal breaker without reviewing the facts.

What Buyers Should Do

Request the relevant title documents, ask questions about any unfamiliar easement, and determine whether a survey would clarify its location. If access depends on an easement, ask your lender and title professional whether the recorded rights satisfy financing and title requirements.

Understanding an easement early can help you avoid surprises about how you may use the property after closing. It also gives your mortgage team time to resolve documentation questions before they affect the loan schedule.

What If My Mortgage Pre-Approval Expires?

A mortgage pre-approval is one of the most valuable tools in your homebuying journey. It’s not just a letter stating how much you’re qualified to borrow; it’s a written commitment from your lender that assures sellers you have the financial backing to make a competitive offer.

Having a pre-approval letter in hand can give you a significant advantage in a competitive housing market, signaling to sellers that you’re serious, financially prepared, and ready to move forward.

However, like many things in life, pre-approval letters have an expiration date. If you don’t find your dream home before that date passes, you may be wondering what your next steps should be.

When Does Pre-Approval Expire?

Pre-approval letters typically expire within 60 to 90 days from the date they are issued. The exact expiration period depends on your lender and personal financial situation. A variety of factors may contribute to the expiration of your pre-approval, including changes in your credit, income, or debt. It’s important to stay mindful of the expiration date so you can plan ahead and ensure you’re still on track for purchasing the home of your dreams.

What Happens If You Don’t Use Your Pre-Approval?

It’s important to remember that just because your pre-approval expires doesn’t mean your home search is over. If you haven’t yet found the right property, or if the market has been particularly competitive, don’t be discouraged.

If your pre-approval expires, all you need to do is refresh it. This is a common step in the homebuying journey and is relatively simple to do. You’ll need to provide updated documentation—such as your most recent bank statements, pay stubs, or any changes to your financial situation—to ensure your pre-approval remains accurate and valid. This allows the lender to reassess your qualifications and ensure you still meet the necessary requirements for a mortgage.

Steps to Take When Your Pre-Approval Expires

  1. Contact Your Loan Officer
    • The first step is to reach out to your loan officer as soon as your pre-approval is about to expire. They’ll be able to guide you through the process of renewing your pre-approval and make sure everything is up to date.
    • Be open and transparent with your loan officer about any changes in your financial or employment situation that might affect your application. This could include a new job, a change in income, or any other significant financial adjustments.
  2. Update Financial Documents
    • Your lender will need to verify your current financial situation before issuing a new pre-approval. To do this, you’ll need to provide your most recent bank statements, pay stubs, tax returns, or other requested materials.
    • These updates will allow the lender to reassess your qualifications and determine if you still meet the criteria for your desired loan program. The more timely and accurate your documents are, the faster the process will go.
  3. Obtain a New Pre-Approval
    • After reviewing your updated documents, your loan officer will issue a new pre-approval letter, which will have an updated expiration date. This new letter will enable you to continue your house-hunting journey with confidence.
    • Keep in mind that your new pre-approval will reflect your current financial standing, so it’s important to stay on top of any changes that could impact your mortgage application.