How a Solar Panel Lease Can Complicate a Home Purchase
Solar panels can be an appealing feature when you are shopping for a home. They may help offset electricity costs, and many buyers like the idea of producing energy on-site. But there is an important difference between buying a house with solar panels that are owned outright and buying one with panels covered by a lease or another financing agreement.

That difference can matter during mortgage approval and long after closing.

Start With Who Owns the Panels

Some homeowners purchase their solar systems outright. Others finance the equipment with a loan, sign a solar lease, or enter into a power purchase agreement under which they pay for the electricity generated. These arrangements can create different payment obligations and responsibilities for maintenance, repairs, and equipment removal.

Do not assume the panels are included in the home sale simply because they are attached to the roof. Ask the seller for the complete solar agreement and any related loan documents before you make a final decision.

Why Your Lender Needs the Details

A lender may need to determine whether the solar equipment is owned, leased, or subject to a lien or other recorded interest. The agreement can affect how the property is valued, what obligations transfer to the buyer, and whether the financing arrangement meets the loan program’s requirements.

If the buyer must assume a monthly solar payment, that obligation may also need to be considered during mortgage qualification, depending on the loan type and agreement. A solar company may require its own approval before a lease or contract can be transferred. These steps can take time, so discovering the arrangement shortly before closing is rarely ideal.

Look Beyond the Monthly Payment

Ask how long the agreement lasts, whether payments increase over time, who maintains the panels, and what happens if the roof needs replacement. Find out whether the contract can be transferred to a new owner, bought out, or terminated, and what each option costs. Review whether the seller is responsible for paying off any balance before closing.

You should also compare recent utility bills with the solar payments to understand the home’s actual energy expenses. Savings advertised in a listing may not match your future usage or the terms you will inherit.

Get the Documents Early

Share the solar paperwork with your lender, real estate agent, and title or closing professional as soon as possible. If you have questions about contract obligations, consider seeking advice from an appropriate legal professional. A solar system does not automatically make a home difficult to finance, but an unclear agreement can create delays.

The goal is simple: know exactly what comes with the home, what you will owe, and what your mortgage lender needs before you commit.
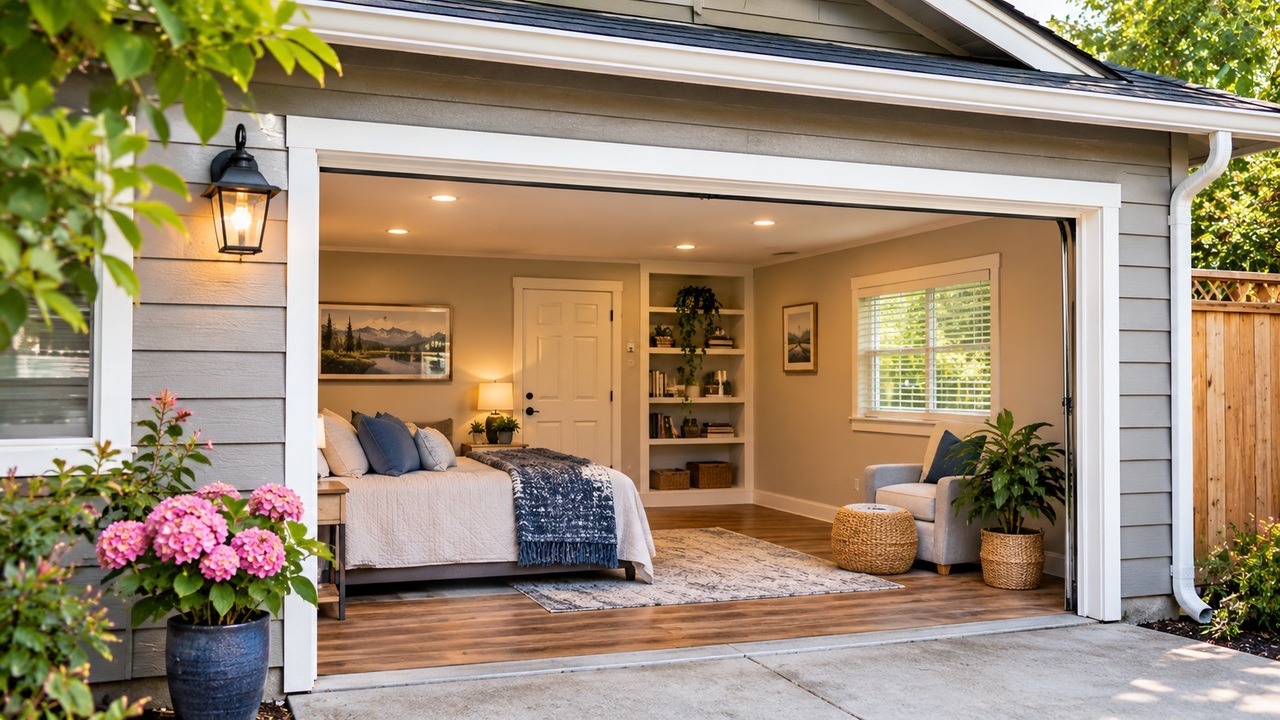
Why an Unpermitted Garage Conversion Can Affect Your Mortgage

A converted garage can make a house feel more useful. It might serve as a bedroom, home office, playroom, or guest space. But before you count that room as part of the home’s living area, there is a question worth asking: Was the conversion properly permitted and approved?
For mortgage purposes, the answer can influence how the property is described, appraised, and reviewed. A room that looks finished is not necessarily recognized as legal living space.

Permits and Living Area Are Different Questions

Local building departments set rules for construction, electrical work, heating, ventilation, windows, and changes in a room’s use. A garage conversion may need permits and inspections, especially when the work changes structural elements or adds plumbing. The rules depend on the location and the scope of the project.

An appraiser may also need to determine whether the converted area meets applicable standards for inclusion in the home’s finished living area. A converted garage may be treated differently from the original house, even if it has attractive flooring and painted walls. It is important not to assume that every finished square foot shown in a listing will be included in the appraisal the same way.

How It Can Affect Financing

If the home’s advertised bedroom count or square footage depends on an unpermitted conversion, the appraised value may not match the asking price. A lender may also have questions about safety, marketability, or whether additional documentation or repairs are necessary. In some situations, the conversion may not prevent financing. In others, unresolved issues could delay approval or change the loan options available.

The details matter, and requirements vary by lender and loan program. That is why buyers should avoid relying on a blanket rule about whether unpermitted work is acceptable.

Questions to Ask Before Making an Offer

Ask the seller when the garage was converted and whether permits were obtained. Request copies of permits, inspection signoffs, and any certificates or records required locally. Compare the listing description with public property records, while remembering that records can sometimes be incomplete or outdated. A qualified home inspector can help identify visible concerns, but only the appropriate local authority can confirm permit status.

Talk with your lender early if the converted space is a major reason you want the property. Ask how it might be treated in the appraisal and whether documentation could be required. Your real estate agent can also help you evaluate the home based on its verified features rather than marketing descriptions alone.

A garage conversion may be a wonderful addition. Understanding how it was completed can help prevent a surprise when financing and appraisal reviews begin.

Veterans Day: Honoring Service and Understanding VA Home Loan Benefits

Veterans Day is an opportunity to recognize the men and women who have served in the United States Armed Forces. Their commitment deserves gratitude that extends beyond a single day. For veterans, active-duty service members, and eligible surviving spouses who are considering homeownership, it is also a meaningful time to understand a benefit that may help them purchase or refinance a home: the VA home loan program.

What a VA Home Loan Does

A VA home loan is generally made by a private lender and backed by a guaranty from the U.S. Department of Veterans Affairs. The guaranty helps eligible borrowers access financing under terms that can differ from conventional mortgages. For many eligible buyers, a VA-backed purchase loan may offer a no-down-payment option, provided the sales price does not exceed the appraised value and the borrower meets lender requirements.

VA loans generally do not require monthly private mortgage insurance. That can make a difference when comparing monthly housing costs. However, a VA funding fee may apply, and certain borrowers qualify for an exemption. Closing costs, property taxes, homeowners insurance, and other expenses still need to be considered.

Eligibility Is the Starting Point

Military service alone does not automatically establish approval for a particular mortgage. Borrowers typically need a Certificate of Eligibility to confirm their VA loan benefit, and the lender reviews income, credit, debts, and the property. Service requirements and surviving-spouse eligibility rules can vary. A lender experienced with VA financing can help explain the steps and request the appropriate documentation.

The Property Matters Too

VA financing is intended for eligible residential use, and the property must meet applicable appraisal and minimum property requirements. An appraisal evaluates value and certain property conditions; it is not a substitute for a comprehensive home inspection. Buyers should still consider an independent inspection so they can understand the home’s condition before closing.

A Thoughtful Way to Explore the Benefit

If you are eligible and thinking about buying, start by asking a qualified lender for a comparison of VA and other available loan options. Look at the interest rate, estimated monthly payment, cash needed at closing, funding fee if applicable, and total borrowing costs. The right choice depends on your circumstances, not simply the loan label.

Today, we honor veterans and their families for their service and sacrifice. Understanding the benefits earned through that service is one practical way to support informed decisions about the next chapter of homeownership.