How an Unfinished Basement Can Affect Your Mortgage Appraisal
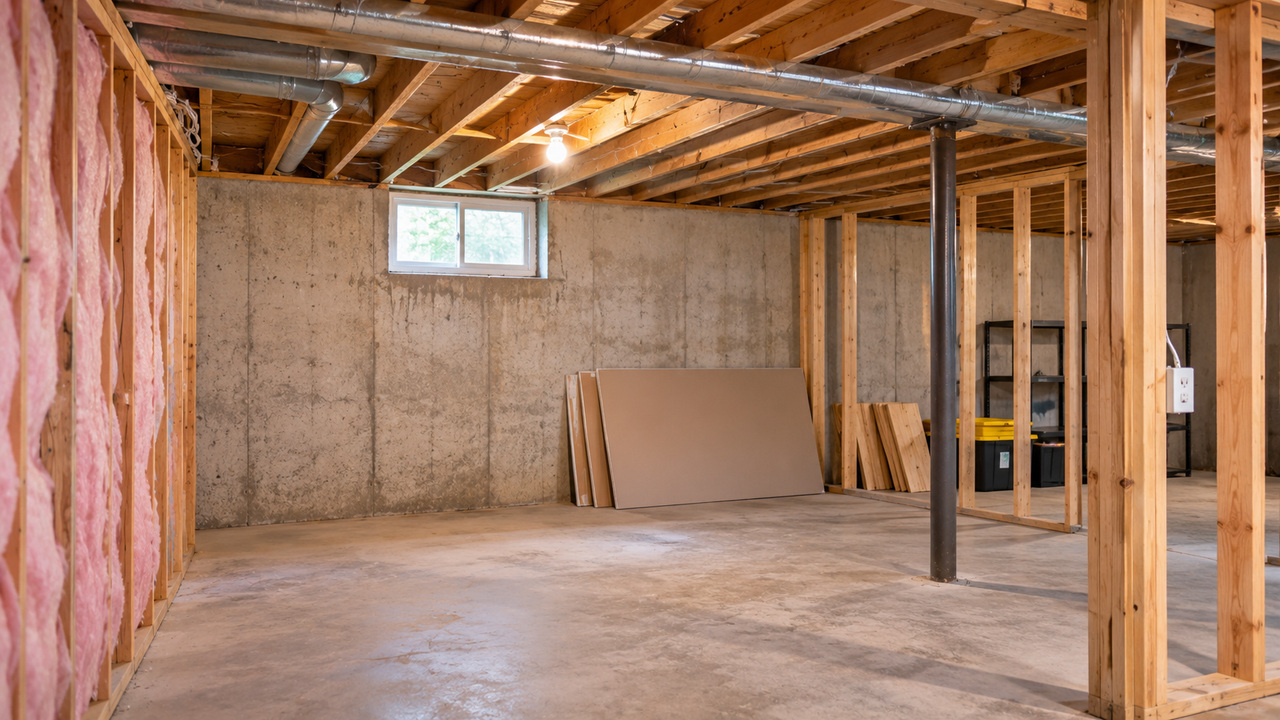
An unfinished basement can look like an opportunity. Buyers may imagine a future family room, guest space, home gym, or office. But when a home is being financed, the appraiser has to evaluate what exists today, not what the basement might become after a renovation. That distinction can affect the home’s reported living area, comparable sales, and ultimately the value used by the lender.

Finished and Unfinished Space Are Not the Same

A basement may be spacious, dry, and useful without qualifying as finished living area. Exposed framing, concrete floors, unfinished ceilings, and incomplete heating or electrical work can all affect how the space is classified. Even a beautifully finished basement may be reported separately from above-grade living area under commonly used appraisal measurement standards. Buyers should not assume that every usable square foot will be counted in the same category.

Why the Listing and Appraisal May Differ

Real estate listings sometimes describe total square footage in ways that include basement areas, while an appraisal may separate above-grade space from below-grade space. That does not necessarily mean either document is trying to mislead anyone. They may be applying different reporting conventions. The distinction matters when buyers compare a home with properties that have similar floor plans but different basement finishes.

Potential Does Not Equal Present Value

A seller may advertise an unfinished basement as space that could easily become an additional bedroom or rental suite. Those possibilities can be appealing, but they are not the same as an existing, legally permitted room. Adding bedrooms or living space may require permits, safe access, proper ceiling heights, emergency egress, and other improvements. An appraiser generally evaluates the current condition and market evidence rather than assigning full value to a project that has not been completed.

How This Can Affect Financing

A lender typically bases its loan-to-value calculation on the applicable appraised value, not simply the agreed purchase price. If the appraisal comes in below the contract price, the buyer may need to discuss options such as renegotiating, bringing additional funds, or reconsidering the purchase. An unfinished basement alone does not mean the home will appraise poorly. The outcome depends on the entire property and how comparable homes are selling.

Questions Worth Asking During a Showing

Find out whether the basement has experienced moisture intrusion, whether any past work was permitted, and which utilities are already installed. Ask for the listed square footage to be broken down between above-grade and below-grade areas. If you plan to finish the basement, obtain realistic estimates and investigate local permit requirements before treating the project as part of your financial plan.

An unfinished basement can be a valuable feature for the right buyer. Just remember that its future possibilities and its current appraised contribution are two different things. Understanding that difference helps you set a realistic budget and avoid surprises during mortgage approval.
Why a Shared Well Can Complicate a Mortgage Approval

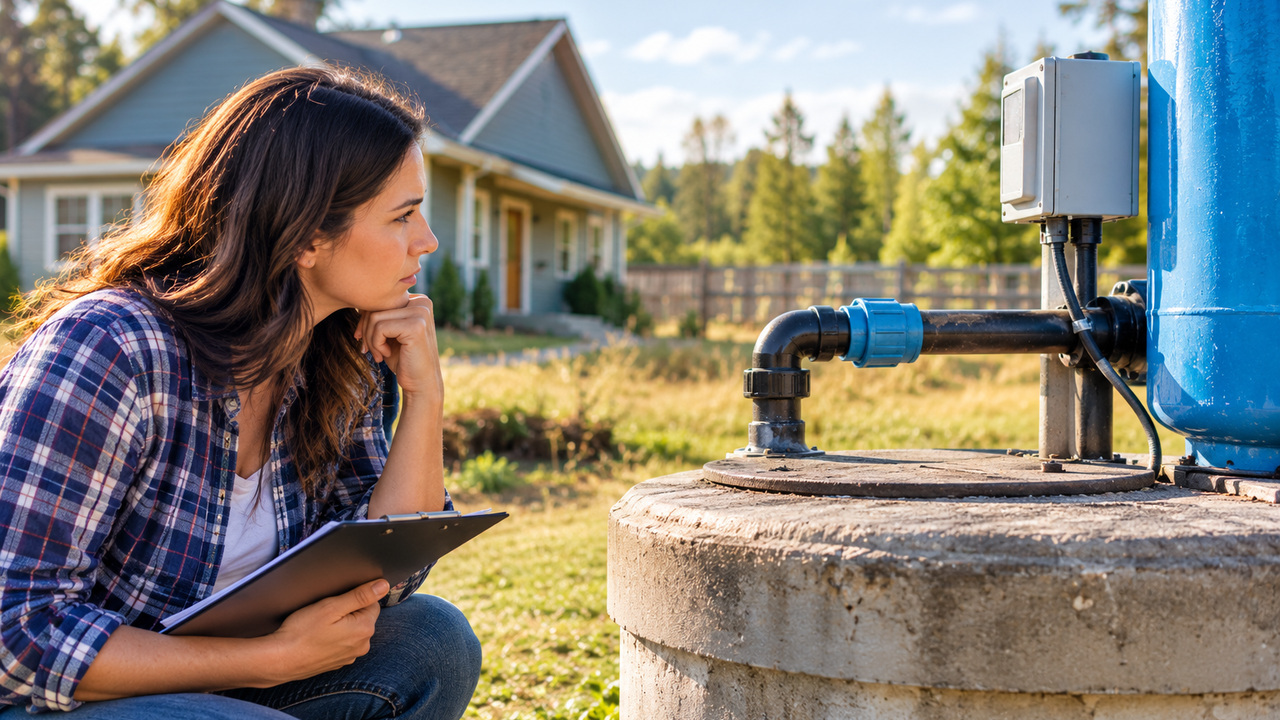
Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.
A Shared Water Source Creates Shared Responsibilities

When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.

Lenders May Ask for Written Documentation

Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.

Water Quality and Supply Still Matter

A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.

What to Check Before You Commit

Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.

It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.

A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.

Can a Home-Based Business Affect Your Mortgage Approval?

A home office, a small workshop, or a room used to meet clients may seem like a normal part of modern homeownership. But when you apply for a mortgage, the way a property is used can matter just as much as how it looks. A home-based business does not automatically prevent financing. The questions usually involve whether the property remains primarily residential, whether its use is permitted, and whether the lender can comfortably evaluate it as a home.

Residential Use Comes First

Most standard residential mortgage programs are designed for properties used primarily as residences. Working remotely from a spare bedroom is generally different from operating a storefront, manufacturing facility, or business that occupies most of the building. Lenders may look at the amount of space devoted to business activity, whether customers visit regularly, and whether the property’s layout still resembles a typical residence.

A detached workshop or converted garage may raise additional questions. For example, a garage with a workbench is different from a building outfitted as a full commercial operation. The distinction is not simply whether someone earns money there. It is how the business use affects the property’s character and marketability.

Zoning and Permits Matter

Local rules can determine which businesses are allowed in residential neighborhoods. Some communities permit low-impact home occupations but restrict signs, employee parking, customer traffic, noise, or storage. A business that violates local zoning requirements may create concerns for a lender or appraiser.

Changes to the property can matter, too. If a homeowner removed a kitchen, built a separate entrance for clients, or converted living space into specialized commercial rooms, the lender may ask whether those changes were properly permitted and whether the property can readily function as a residence.

What the Appraiser Evaluates

An appraiser considers the property as it exists, including its layout, condition, and appeal to typical buyers in the area. Unusual business improvements do not necessarily add the same value that they cost to install. Highly specialized features may even make comparable sales harder to identify.

The appraiser may also note whether the business area can be converted back to ordinary residential use. A flexible home office often presents fewer valuation questions than permanent alterations designed for a narrow commercial purpose.

Income Is a Separate Question

If you own the business, your self-employment income may require additional documentation. That is a borrower qualification issue, separate from whether the property itself is acceptable collateral. A lender may review tax returns, business financials, or other records to evaluate qualifying income, depending on the loan program.

Questions to Ask Before You Buy

Ask how the property is zoned, whether business-related improvements have permits, and whether any homeowners association limits commercial activity. Share the intended use with your mortgage professional early, especially if the business requires dedicated facilities or frequent visitors.

A home-based business and a residential mortgage can often coexist. The safest approach is to confirm that the property remains suitable for residential financing before relying on an assumed approval timeline.