What to Expect During the Mortgage Approval Process
Getting pre-approved is an important step in the homebuying journey, but it is only the beginning of the mortgage process. Many buyers are surprised by what happens next and are not fully prepared for the steps involved in final approval.

Understanding what to expect can help you stay on track and avoid delays that could impact your ability to close on your home.

Pre-Approved Versus Fully Approved
A pre-approved mortgage gives you an estimate of what you can borrow based on your initial financial information. However, full approval happens later in the process after a deeper review. Lenders will verify your income, assets, and credit in more detail. Knowing the difference helps set the right expectations and prevents confusion as you move forward.

The Role of Underwriting
Underwriting is the stage where your loan is carefully reviewed by the lender. During this process, all financial information is verified to ensure it meets lending guidelines. This includes reviewing your employment, income stability, credit history, and debt-to-income ratio. Underwriting is a critical step that determines whether your loan will be fully approved.

Why Documentation Is So Important
During the approval process, you will likely be asked to provide additional documents. This can include bank statements, pay stubs, and explanations for certain transactions. While this may feel repetitive, it is a normal part of the process. Providing accurate and timely documentation helps keep everything moving forward.

Avoid Changes During the Process
One of the most important things you can do during this time is maintain financial stability. Avoid changing jobs, taking on new debt, or making large purchases. Even small changes can impact your approval status. Staying consistent helps ensure that your loan remains on track.

Stay Responsive and Communicate
Clear and timely communication with your lender is essential. Responding quickly to requests and staying engaged throughout the process can prevent unnecessary delays. The more proactive you are, the smoother your approval process will be.

Understanding the mortgage approval process helps you move forward with confidence and avoid surprises along the way. Ready for a mortgage? Give us a call today to get started.
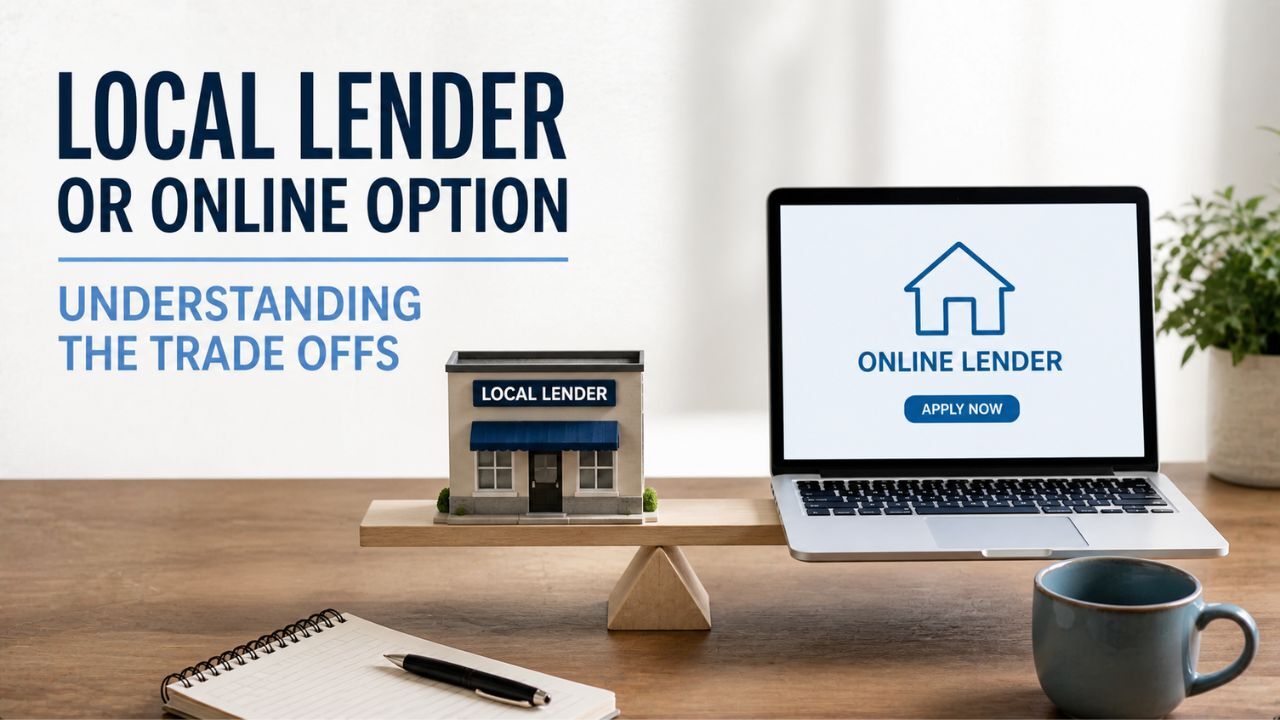
Local Lender or Online Option? Understanding the Trade-Offs

Choosing the right lender is a critical part of the homebuying process, and many buyers find themselves deciding between a local lender and an online option. While both can provide financing, the experience, level of service, and overall support can vary significantly.
Understanding the tradeoffs allows you to choose the option that best fits your needs and helps ensure a smoother transaction from start to finish.

The Value of Working with a Local Lender
Local leaders often provide a more personalized and hands-on experience. You typically have direct access to a loan officer who understands your situation and can guide you through each step of the process.

Communication is often faster and more consistent, which can be especially important when timelines are tight. Local lenders also tend to have a stronger understanding of the market, which can be helpful when navigating appraisals and closing timelines.

The Convenience of Online Lenders
Online lenders are known for their speed and accessibility. Many offer streamlined applications that can be completed quickly, sometimes with faster initial approvals. For buyers who prefer a digital experience and minimal in person interaction, this can be appealing. However, communication may be less direct, and you may not always work with the same representative throughout the process.

Comparing Rates, Fees, and Flexibility
It is important to compare both options carefully when it comes to rates and fees. While online lenders may advertise competitive rates, the overall cost of the loan can vary depending on fees and terms. Local lenders may offer more flexibility and be better positioned to adjust to unique financial situations. Looking at the full picture rather than just the rate helps you make a more informed decision.

Communication Can Make or Break the Process
One of the biggest differences between the two options is communication. A responsive lender who keeps you informed can make the process feel smooth and manageable. Delays or lack of clarity, on the other hand, can create unnecessary stress. Consider how important accessibility and guidance are to you when making your choice.

Choosing the Right Fit for Your Situation
There is no one size that fits all answer when it comes to selecting a lender. Some buyers value convenience, while others prioritize personal support and guidance. Evaluating your priorities will help you determine which option aligns best with your expectations and comfort level.

Choosing the right lender can impact your entire homebuying experience, from application to closing. Ready for a mortgage? Give us a call today to explore your options.

Tips to Remember When Shopping for a New Home Loan

Finding a new home loan can seem challenging, but if you take the proper steps before you start applying for loans, you’ll have no difficulty finding a mortgage that works for you and a lender that would love to have you as a borrower. Shopping for a mortgage isn’t like shopping for a couch, and there’s a lot that goes into the process.

So how can you shop for your new home loan in a way that saves you time and gets you the best loan for your needs? Here’s what you need to know.

Research Loan Types
A lot of home buyers, especially first-time buyers make the mistake of not doing their research and not asking enough questions. A fixed-rate mortgage isn’t right for every homebuyer. Neither is an adjustable-rate mortgage. If you plan to stay, put in a home to raise a family, you might consider a 30-year loan.

Conversely, if you’re moving in 10 years or less, an adjustable-rate mortgage, or ARM, could better suit you. It’s advised that you research loan types then prepare a list of questions to ask your mortgage agent to ensure you select the loan that’s best for you.

Get Pre-Qualified Before You Start Looking
It can be tempting to start looking for mortgages online and start seeing what kinds of rates and limits you can afford, but if you start your mortgage hunt with Internet window-shopping, you may end up sorely disappointed. A pre-qualification is a vital first step that can help you to find the mortgage that works best for you. With a pre-qualification, you’ll have a good idea of what you can reasonably afford to spend on a home, so you won’t waste time viewing homes that are outside of your price range.

Hold Off On Major Life Changes Until You Have Your Mortgage
Once you’ve been pre-qualified and pre-approved, the next step is the approval process, the part of the process where the lender you’ve chosen evaluates your application and decides whether or not to lend to you. One mistake that a lot of homebuyers make is allowing significant changes in their income to happen during the approval process. If you quit your job to start a business, or if you go down to part-time hours so you can spend more time with the kids, your lender will need to start the approval process again with your new financial information in mind, so hold off on any big changes until you’ve been approved.

Finding a new home loan can seem like a challenge, but a qualified mortgage advisor can help. Contact your local mortgage professional to learn more.