Why a Shared Well Can Complicate a Mortgage Approval
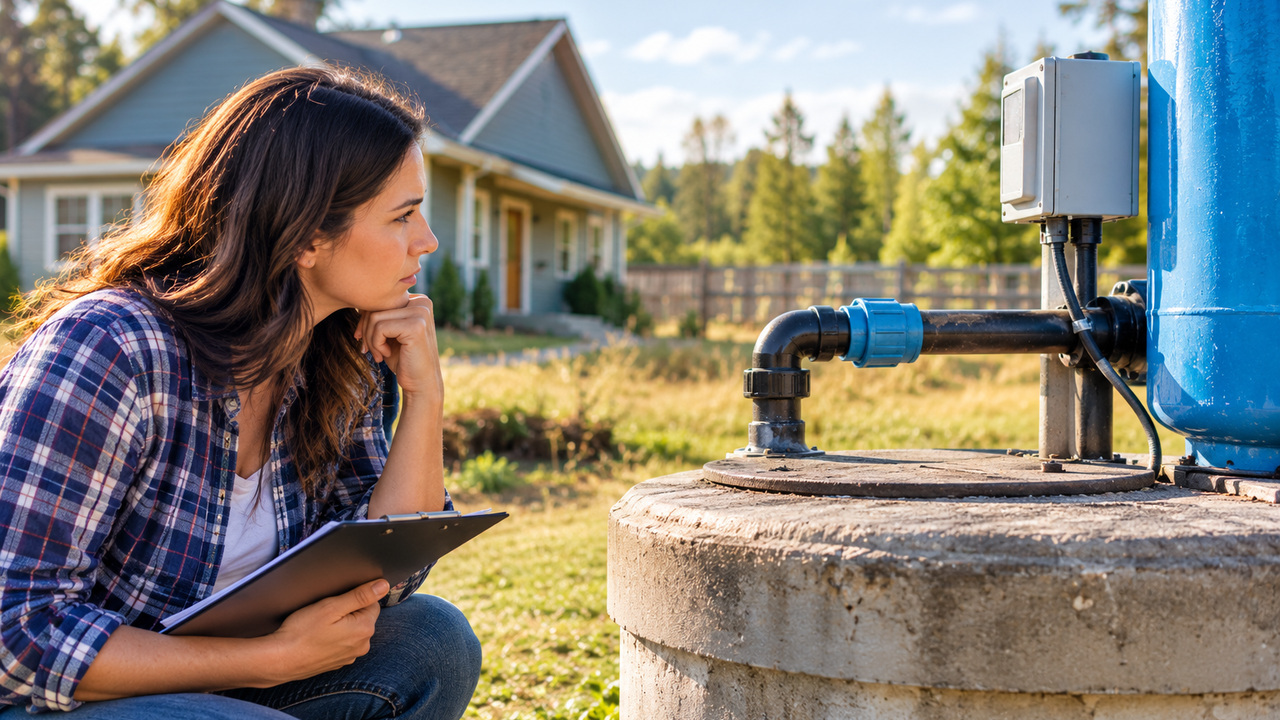
Buying a home with a private well can feel straightforward until you discover that the water source is shared with a neighboring property. Shared wells are common in some rural and semi-rural communities, but they can introduce questions that buyers of homes with municipal water may never encounter. A lender may need to understand not just whether the water works today, but whether the property has a dependable legal right to use it in the future.

A Shared Water Source Creates Shared Responsibilities

When two or more homes rely on the same well, ownership and maintenance responsibilities may be divided among the property owners. One household might have the well equipment on its land while another depends on a pipeline crossing the property line. That arrangement can work well for years, especially when neighbors cooperate. Problems can arise, however, if there is no clear agreement about repairs, electricity costs, access, or what happens when someone sells.

Lenders May Ask for Written Documentation

Depending on the loan program and property circumstances, a lender may request a recorded shared-well agreement or other documentation establishing access and responsibilities. The agreement may address who can use the well, who pays for upkeep, how repairs are approved, and whether each property can continue receiving water if ownership changes. Requirements vary, so buyers should avoid assuming that a handshake arrangement between neighbors will satisfy a lender.

Water Quality and Supply Still Matter

A shared-well agreement does not replace questions about the water itself. A lender, appraiser, or local authority may require information about water quality or whether the system can adequately serve the connected homes. Testing requirements can depend on the loan type, local rules, and property conditions. Buyers may also want to ask about the age of the pump, past interruptions, and whether the system has enough capacity during heavy use.

What to Check Before You Commit

Ask early whether the property uses a private well, a shared well, or a community water system. If it is shared, request copies of existing agreements and find out where the well and water lines are located. Ask who pays the electric bill, whether there is a maintenance fund, and how emergency repairs are handled. A title professional or real estate attorney may help clarify whether necessary access rights are documented.

It is also wise to raise the issue with your lender before the transaction is far along. Discovering a missing agreement shortly before closing can create delays while the parties gather signatures or resolve ownership questions.

A home served by a shared well is not automatically difficult to finance. The key is making sure the water supply is reliable and the arrangement is clear enough for everyone involved. A little investigation early in the buying process can prevent a surprisingly complicated issue from surfacing just as you are preparing to move.
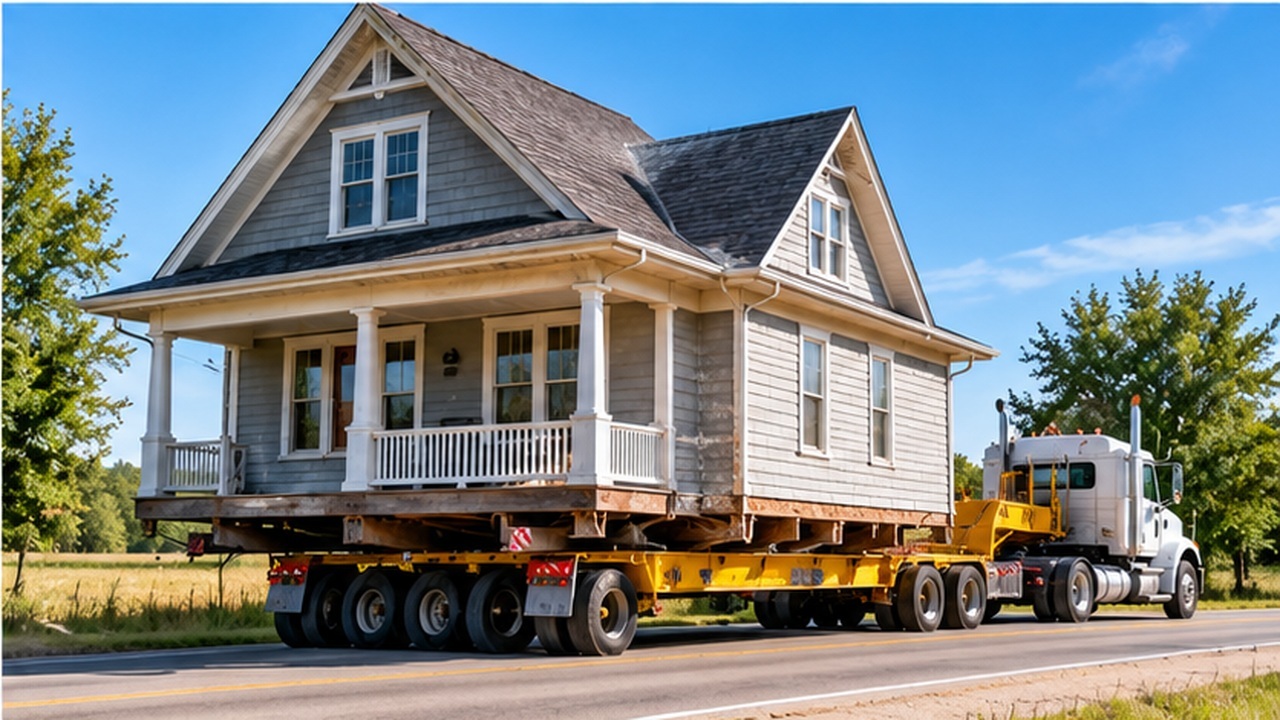
Can You Get a Mortgage on a Home That Has Been Moved From Another Location?

Most buyers assume that the home they are purchasing has always been located on its current property. However, some houses have been physically relocated from one location to another.
Whether a historic home was preserved by moving it or an existing structure was transported to a new lot, the property’s relocation history can create unique questions during the mortgage process.

Why Would Someone Move an Entire House?
Moving an existing home is more common than many people realize, particularly in areas where older houses are preserved or land is being redeveloped.

Instead of demolishing a structure, an owner may hire specialized contractors to lift the house, transport it, and place it on a new foundation.

In other situations, a house may be relocated to make room for construction or to preserve a building with historical significance.

Although the home may look completely normal once the project is finished, its relocation history can still be relevant when applying for financing.

The Foundation Can Be an Important Factor
When a home is moved, it generally must be placed on a suitable foundation at its new location.

Mortgage lenders and appraisers may need to evaluate whether the foundation and structure meet applicable requirements.

Depending on the property and loan program, additional documentation may be requested regarding the foundation, building permits, inspections, and completed relocation work.

Buyers should not assume that a home is automatically eligible for financing simply because it has been occupied since the move.

Property Records May Need Clarification
A relocated house may have a construction history that differs from the records associated with its current lot.

For example, the house may have been originally built decades earlier but moved to its present location much more recently.

The lender or appraiser may need to understand the difference between the original construction date and the date of relocation.

Permit records, certificates of occupancy, and other local documentation may help establish that the relocation was completed appropriately.

Missing or inconsistent information could lead to additional questions before the mortgage is approved.

Appraising a Relocated Home
Determining market value may also require careful consideration.

The appraiser evaluates the property in its current location and condition, rather than relying solely on what the structure may have been worth before it was moved.

Factors such as the foundation, overall condition, neighborhood, available comparable sales, and quality of completed work can influence the valuation.

A relocated house is not automatically worth less, but unusual property characteristics may require additional analysis.

What Buyers Should Do Before Applying
Buyers interested in a relocated home should ask when the move occurred, who performed the work, and what documentation is available.

They should also discuss the home’s history with their mortgage professional before committing to a financing timeline.

For buyers who appreciate unique or historic properties, a relocated home can offer considerable charm. The key is understanding the property’s history and confirming that its current condition and documentation support the intended mortgage financing.

Why Buying a Home From a Family Member Can Make the Mortgage More Complicated

Buying a home from a parent, grandparent, sibling, or another relative may seem easier than purchasing from a stranger. You already know the seller, may know the property’s history, and might even agree on a price without extensive negotiations.

But the family relationship can introduce mortgage considerations that are different from those in a typical purchase between unrelated parties.

The Relationship Matters
A transaction between people with an existing relationship may be considered differently from a traditional arm’s-length sale.

That does not mean family transactions are prohibited. It means the lender may need to understand the relationship between the buyer and seller and review the structure of the transaction accordingly.

Being clear about the relationship from the beginning is important.

A Gift of Equity May Be Possible
One feature sometimes associated with family transactions is a gift of equity.

Instead of giving the buyer cash for a down payment, an eligible family member selling the property may be able to provide a portion of the home’s equity as a gift within applicable mortgage guidelines.

How a gift of equity can be used depends on the mortgage program and transaction, and documentation requirements can apply.

Buyers should discuss the proposed structure before agreeing on final numbers.

The Appraisal Still Matters
A family member may be willing to sell a property for less than they believe it is worth, but the agreed price does not eliminate the appraisal process when an appraisal is required.

The property still needs to be evaluated independently for the mortgage transaction.

That can become particularly important when a gift of equity or below-market sale is involved.

Treat It Like a Financial Transaction
Family relationships can make buyers and sellers more comfortable relying on verbal agreements.

A home purchase is too significant for assumptions.

Make sure the purchase price, credits, responsibilities, timelines, and other terms are properly documented through the appropriate transaction paperwork.

Buying a relative’s home can create an opportunity that would never reach the open market. It can also allow a property with family history to remain within the family.

The key is to remember that familiarity between buyer and seller does not eliminate the mortgage process.

Discuss the family relationship, proposed purchase price, and any planned gift of equity with your mortgage and real estate professionals early so the transaction can be structured correctly from the beginning.