Can a Detached Garage Affect Your Home’s Mortgage Appraisal?
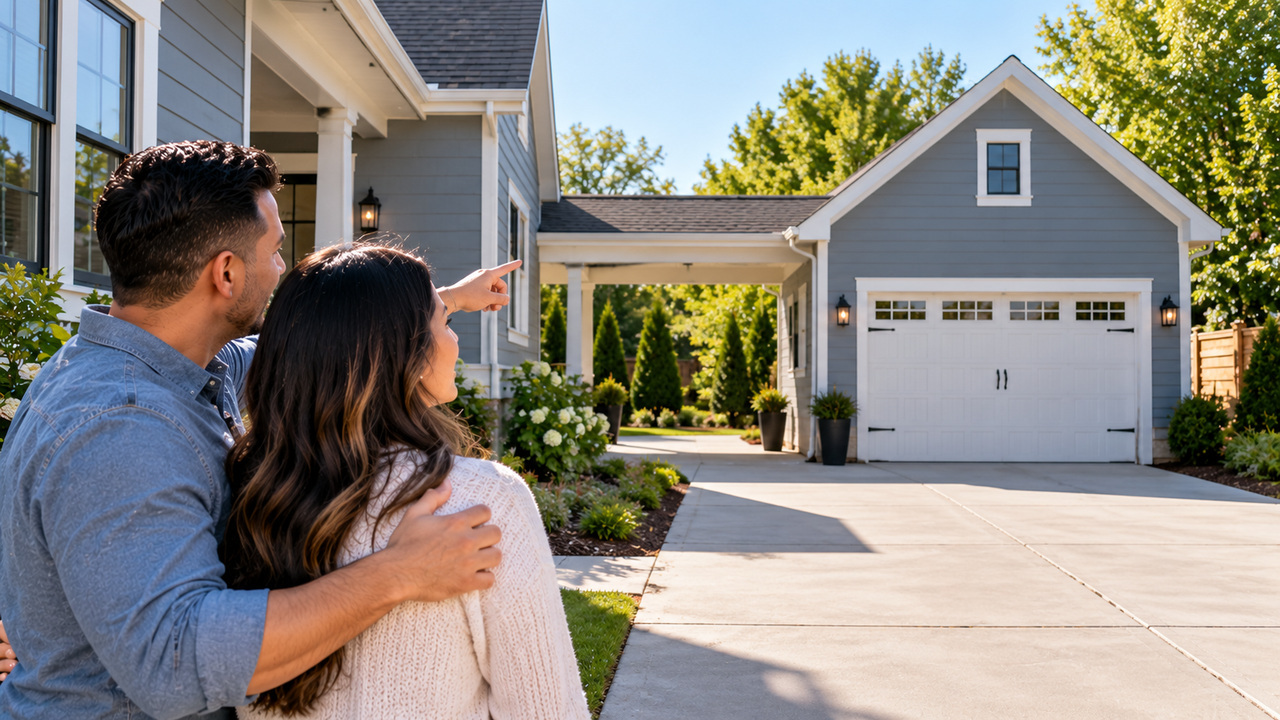
A detached garage can be a major selling point. It may provide covered parking, extra storage, or room for hobbies and projects. But buyers sometimes assume that every square foot of a detached structure adds value in the same way as living space inside the house. During a mortgage appraisal, the analysis is more specific. The appraiser looks at the structure’s condition, function, and contribution to market value.

A Garage Is Not the Same as Living Area

A detached garage is generally evaluated separately from the home’s finished living area. Even if it has electricity, insulation, or finished walls, that does not automatically make it part of the residence’s gross living area.

The distinction is important because listing descriptions sometimes combine different types of space in ways that sound impressive but do not match appraisal reporting standards. A 2,000-square-foot house with a 600-square-foot detached garage is not necessarily a 2,600-square-foot home for appraisal purposes.

Condition and Construction Count

An appraiser may note the garage’s size, construction quality, accessibility, and overall condition. A well-maintained structure with a functional door and sound roof can appeal to buyers. A building with foundation damage, water intrusion, or unsafe wiring may present a different picture.

The appraiser also considers whether the structure is typical for the neighborhood. A detached two-car garage may be highly desirable where off-street parking is scarce. In an area where nearly every home has a similar garage, it may be viewed as a standard feature rather than a premium upgrade.

What About Workshops and Converted Garages?

Some detached garages have been converted into workshops, studios, or other specialized spaces. These improvements may be useful to a particular owner, but they do not necessarily contribute their full construction cost to market value.

If a structure has plumbing, a bathroom, or sleeping quarters, the lender and appraiser may need to understand whether the work was permitted and how the space is legally classified. A finished room over a garage, for example, may be treated differently depending on its access, utilities, local requirements, and the applicable appraisal standards.

Permits and Safety Can Raise Questions

Unpermitted additions or unsafe conditions can complicate a transaction. The exact response depends on the loan program, the property, and the nature of the issue. A lender might request documentation, further evaluation, or repairs before closing.

Buyers should also check whether a detached structure sits within property boundaries and complies with setbacks or other local rules. These questions are especially relevant when the garage was added long after the original home was built.

How Buyers Can Prepare

Before making an offer, ask about the garage’s age, permits, known repairs, and current use. If the structure is a major reason you want the property, discuss it with your mortgage professional and avoid assuming it will support a specific increase in appraised value.

A detached garage can absolutely make a home more useful and appealing. Its value in a mortgage appraisal, however, comes from market evidence and the structure’s actual characteristics, not simply its square footage or replacement cost.
Can a Home-Based Business Affect Your Mortgage Approval?

A home office, a small workshop, or a room used to meet clients may seem like a normal part of modern homeownership. But when you apply for a mortgage, the way a property is used can matter just as much as how it looks. A home-based business does not automatically prevent financing. The questions usually involve whether the property remains primarily residential, whether its use is permitted, and whether the lender can comfortably evaluate it as a home.
Residential Use Comes First

Most standard residential mortgage programs are designed for properties used primarily as residences. Working remotely from a spare bedroom is generally different from operating a storefront, manufacturing facility, or business that occupies most of the building. Lenders may look at the amount of space devoted to business activity, whether customers visit regularly, and whether the property’s layout still resembles a typical residence.

A detached workshop or converted garage may raise additional questions. For example, a garage with a workbench is different from a building outfitted as a full commercial operation. The distinction is not simply whether someone earns money there. It is how the business use affects the property’s character and marketability.

Zoning and Permits Matter

Local rules can determine which businesses are allowed in residential neighborhoods. Some communities permit low-impact home occupations but restrict signs, employee parking, customer traffic, noise, or storage. A business that violates local zoning requirements may create concerns for a lender or appraiser.

Changes to the property can matter, too. If a homeowner removed a kitchen, built a separate entrance for clients, or converted living space into specialized commercial rooms, the lender may ask whether those changes were properly permitted and whether the property can readily function as a residence.

What the Appraiser Evaluates

An appraiser considers the property as it exists, including its layout, condition, and appeal to typical buyers in the area. Unusual business improvements do not necessarily add the same value that they cost to install. Highly specialized features may even make comparable sales harder to identify.

The appraiser may also note whether the business area can be converted back to ordinary residential use. A flexible home office often presents fewer valuation questions than permanent alterations designed for a narrow commercial purpose.

Income Is a Separate Question

If you own the business, your self-employment income may require additional documentation. That is a borrower qualification issue, separate from whether the property itself is acceptable collateral. A lender may review tax returns, business financials, or other records to evaluate qualifying income, depending on the loan program.

Questions to Ask Before You Buy

Ask how the property is zoned, whether business-related improvements have permits, and whether any homeowners association limits commercial activity. Share the intended use with your mortgage professional early, especially if the business requires dedicated facilities or frequent visitors.

A home-based business and a residential mortgage can often coexist. The safest approach is to confirm that the property remains suitable for residential financing before relying on an assumed approval timeline.

How Leased Solar Panels Can Affect Your Mortgage Approval

Solar panels can make a home attractive to buyers who want to manage electricity costs. But the panels on a roof are not always owned by the seller. When a solar system is leased or covered by another third-party agreement, buyers may need to review additional paperwork before their mortgage can be finalized.

Owned and Leased Systems Are Different

With an owned solar system, the homeowner generally owns the equipment, although there may still be a loan secured by the system or property. With a lease, a separate company typically owns the panels while the homeowner pays to use them.

A power purchase agreement is another arrangement in which the homeowner may pay for electricity generated by equipment owned by a third party.

These distinctions matter because a buyer may be asked to assume a contract rather than simply acquire equipment as part of the home purchase.

Why Mortgage Lenders Review the Agreement

A lender needs to understand whether the solar arrangement creates ongoing payment obligations, affects title, or gives another party rights involving the property.

Depending on the loan program, the lender may request the solar lease, payment terms, transfer requirements, and documentation about any recorded notices or security interests. The appraiser may also need to treat leased equipment differently from panels owned outright.

A solar contract does not automatically prevent mortgage approval, but missing paperwork or unclear terms can slow the process.

What Happens When the Home Is Sold?

Some solar agreements allow a qualified buyer to assume the existing contract. Others may offer a buyout or require the seller to complete steps before ownership changes.

Buyers should ask whether the provider must approve the transfer, whether payments can increase, how long the agreement lasts, and who handles maintenance or roof-related work. A low introductory payment is only one part of the financial picture.

Look Beyond the Electricity Bill

Before making an offer, request copies of the full solar agreement and recent utility bills. Find out whether there are production guarantees, insurance requirements, roof access provisions, or costs associated with removing and reinstalling panels.

Share the documents with your mortgage professional and closing team as early as possible. It is also wise to confirm who will be responsible for any remaining obligations after closing.

Solar panels may offer real benefits, but a lease is a continuing contractual commitment. Understanding that commitment before purchasing helps buyers evaluate the total cost of the home and avoid unexpected financing complications.